A buyer's journey, and where a BNPL-only offer may not fit a larger project
Follow the customer: one bathroom, one finance option
A fictional buyer's journey, and where a BNPL-only offer may not fit a larger project
Meet Sam. He’s not real; we made him up, but we’re using our fictitious friend to illustrate a typical sales journey many customers and businesses experience daily.
So, it’s story time. Are you sitting comfortably? Then we’ll begin.
Sam has lived with a tired bathroom for years and has finally decided he can’t live with the same tired old tiles and shoddy shower, and he wants to do something about it.
His plans go way beyond shiny new taps and a fresh coat of paint; he’s planning to go to town, the whole enchilada: new suite, new tiles, new shower, new rubber duck.
Because it’s a big project, Sam isn't in a rush; it’s a big decision, and he’s determined to get it right, not just the colour of the tiles but also how much and how he pays.
Stage one: the showroom
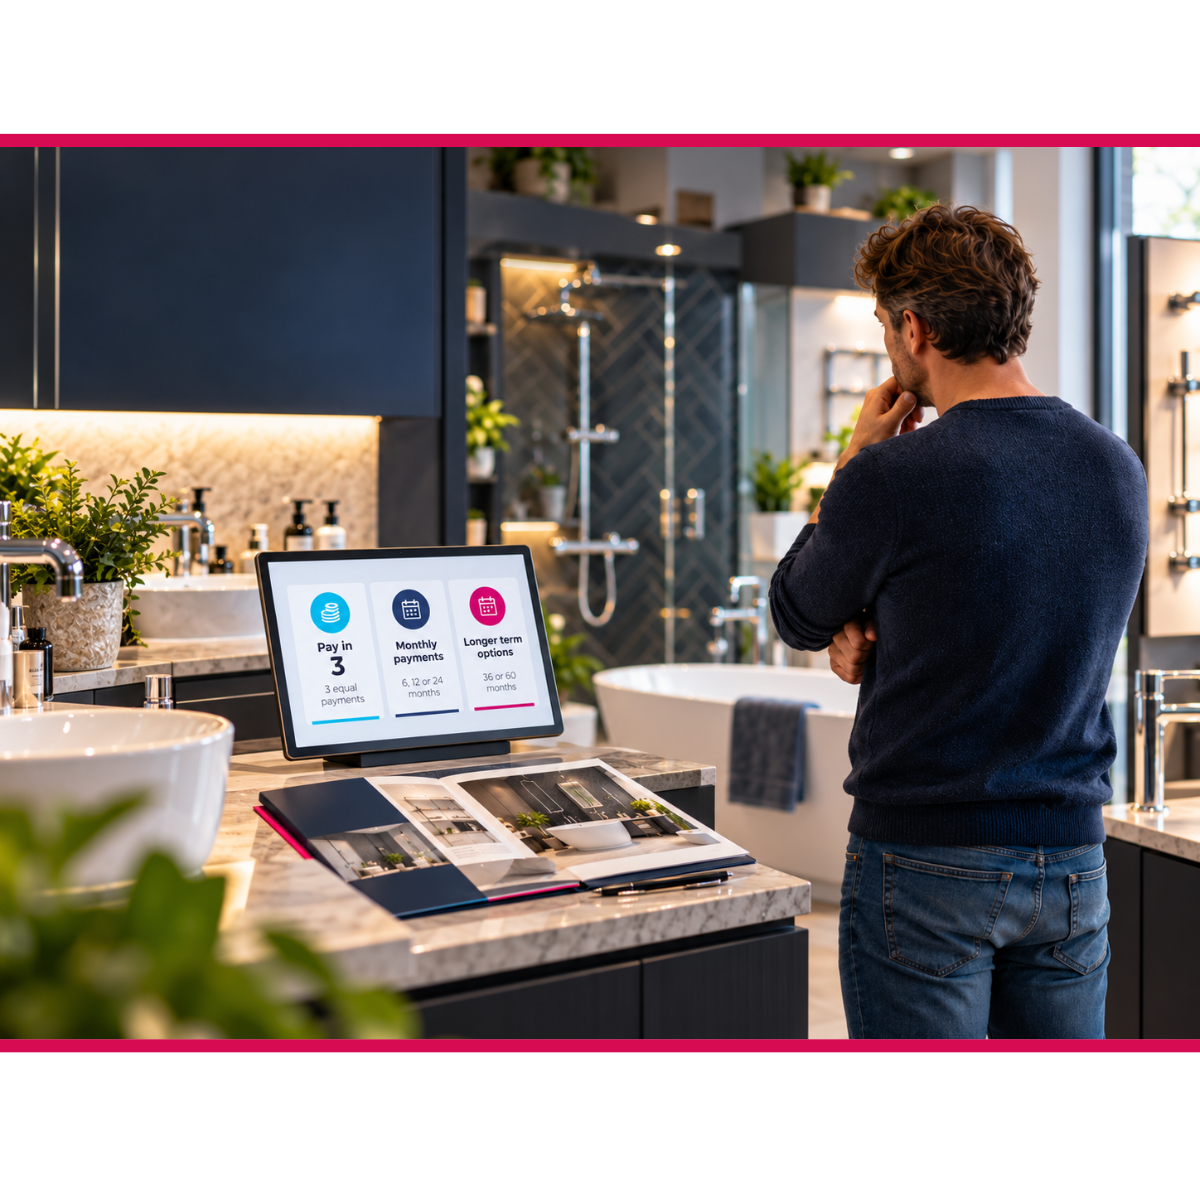
Sam sets off to visit his local showroom on a Saturday morning. He’d often gazed longingly at the loos and swooned over the sinks, but today he’s stepping through the doors to choose his perfect suite.
The displays are eye-catching, and the staff are extremely helpful. Near the till, there's a sign for pay in three instalments.
For a smaller purchase, that might be the best option. For a whole bathroom, though, Sam isn't so sure.
Three payments on a full refit is still a lot of money in a short space of time, so he thanks the staff for their help, takes a brochure and books a design appointment.
Subhead: Stage two: the design appointment
The designer knows his bathrooms. He talks through layouts, products and finishes, and Sam feels like the designer understands his vision perfectly. As everything is going so well, Sam asks the designer whether there's a way to spread the cost over a longer period.
The designer says, if they’re honest, they’re not really sure. The only option they know about is Pay in Three. They suggest the best thing Sam can do at this stage is to ask again when the quote comes through.
Stage three: the quote
The quote arrives. It's within the range Sam expected, but the only finance option on the quote is the same short-term one. He doesn't say no; he just says he needs time to think about it.
Stage four: thinking it over
At home, Sam starts to explore what else is out there. Some businesses he looks at show finance options with different terms. Some don't show any at all. He still hasn't decided anything yet, but the showroom is no longer the only option in mind. Suddenly that initial sale seems a lot less straightforward than when he first walked through the showroom door.
What Sam's journey tells us
Firstly, there were no clear red flags in Sam’s journey. The staff were helpful, the product was right, and the price was fair. From our experience, it’s very similar to the way many businesses operate.
So even though everyone in Sam’s journey was doing their job correctly, at three separate points, the finance offer didn't quite fit the size of the project. That’s three missed opportunities to secure the sale. So where exactly did the process not deliver?
At the showroom, the only option on display suited smaller purchases.
At the design stage, staff weren't sure what else they could offer.
At the quote, Sam had no choices to weigh up, leaving the sale up in the air.
For many retailers, BNPL can be a useful option in their sales arsenal. The real question is whether, on its own, it fits the way larger projects are bought.
A good moment to review
Since 15 July 2026, deferred payment credit, often called BNPL, has been a regulated credit agreement. For businesses that offer it, if you’ve yet to review your current offering, now is a great time to review your customer journey so you can answer the following with confidence.
Do you have the right permissions for what you offer?
Are your financial promotions approved and accurate?
Do your staff know what they can and can't say about finance with confidence?
Does one option suit your largest projects, or could a wider credit offering support customer choice?
We looked at what the regulation means in more detail in our earlier article; BNPL regulation is not just a deadline. It is a retail finance reset.
https://www.productpartnerships.com/insights/bnpl-regulation-is-not-just-a-deadline-it-is-a-retail-finance-reset/
How PPL can help
PPL helps kitchen, bathroom and home improvement businesses review and refine their finance proposition, set up the right regulatory structure and, as a credit broker, access lenders on our panel. Our Artemis platform supports financial promotions approval, complaints handling and staff training.
We can help ensure everyone from your sales team to designers understands what they can discuss with your customers and that there’s consistency across the business at every touchpoint.
If you recognise customer journeys like Sam's and feel you’ve got room for improvement regarding giving customers that all-important choice in a crowded and competitive market, it may be worth a conversation.
Talk to PPL about finance for home projects
Related News

New Protections for Buy Now Pay Later Borrowers
From 15 July 2026, Buy Now Pay Later (BNPL) products, formally defined in legislation as Deferred Payment Credit, will fall within the regulatory perimeter of the Financial Conduct Authority (FCA).

Supreme Court Ruling Clarifies Car Finance Commission Disputes
A recent Supreme Court decision has brought welcome clarity to the legal landscape around motor finance commissions, with implications for dealers, lenders, and consumers alike.

Think Compliance acquisition supports PPL growth strategy
Think Compliance acquisition supports PPL growth strategy